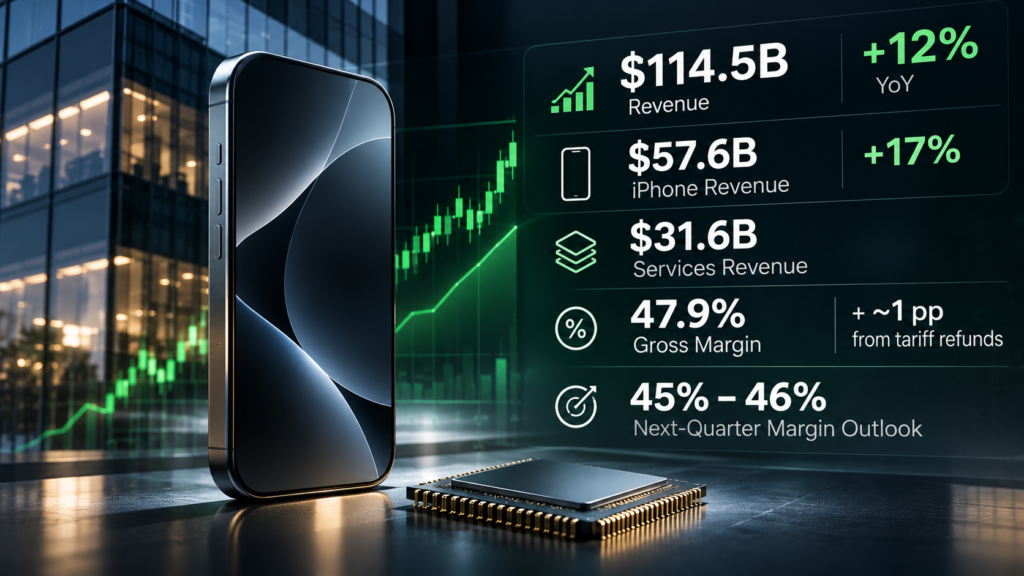
Apple delivered record September-quarter revenue as strong iPhone demand and continued growth in Services helped the technology group exceed Wall Street expectations. However, rising memory-chip costs and a lower margin outlook suggest that maintaining profitability could become more challenging.
Key Points
◉ Revenue reached $114.5 billion, up 12% year over year, beating analyst expectations.
◉ Company Apple expects gross margin of 45%–46% for the December quarter, highlighting rising component costs.
Record Revenue, Strong iPhone Demand
Apple reported fiscal fourth-quarter revenue of $114.5 billion for the period ended September 26, 2026, compared with approximately $102.5 billion a year earlier. Diluted earnings per share rose 14% to $2.10. Both figures exceeded analyst expectations, according to market reporting.
The iPhone remained the central growth driver. Revenue from the product reached $57.6 billion, increasing approximately 17% year over year. The result reflected demand for the iPhone 18 Pro lineup, although supply constraints limited the company’s ability to meet demand fully.
Mac revenue also outperformed expectations, reaching $10.8 billion. By contrast, iPad revenue declined to $6.2 billion, while Wearables, Home and Accessories generated $8.3 billion, reflecting softer performance in those categories.
Services Strengthens Revenue Mix
Services revenue reached approximately $31.6 billion, setting another record and reinforcing the importance of Apple’s ecosystem beyond hardware sales.
Recurring revenue from digital services helps diversify the company’s business, reducing its dependence on individual device launches. However, the latest results also underline how much Apple’s overall performance remains connected to iPhone demand, product availability and consumers’ willingness to pay for premium devices.
Margin Pressure Moves Into Focus
Apple reported a gross margin of 47.9%, but the headline figure requires context. The company said tariff refunds contributed approximately one percentage point to the margin, while $0.05 of diluted earnings per share benefited from those refunds.
Meanwhile, higher memory-chip prices are becoming a more significant cost consideration. Apple has raised some product prices, helping offset component inflation, but the extent to which pricing can absorb further cost increases remains an important question.
For the December quarter, Apple forecast gross margin of 45%–46%. It also expects revenue to grow 7%–10% year over year, with Services growth projected at 8%–9%. The margin outlook suggests that strong demand may not translate directly into the same level of profitability.
The Next Test
Apple’s fiscal 2026 revenue reached approximately $478.8 billion, while quarterly operating cash flow was about $28 billion. The company also returned $28 billion to shareholders during the quarter, demonstrating the scale of its cash generation.
The next phase will test whether Apple can sustain its sales momentum while managing higher component costs and investing in artificial intelligence features, including its updated Siri experience. Supply availability will also matter during the holiday quarter, traditionally a key period for device sales.
The latest results demonstrate strong demand and a resilient ecosystem. Yet the projected decline in gross margin makes cost management, product mix and supply constraints central factors in assessing Apple’s near-term financial performance.