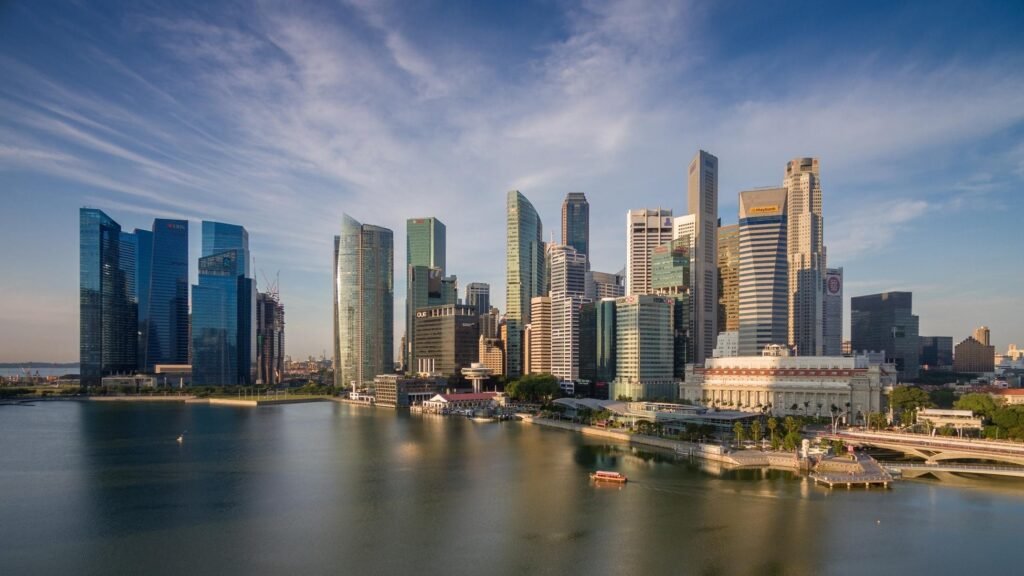
Singapore’s largest banks are facing mounting pressure as investors reconsider the outlook for earnings, dividends and valuations following a sharp decline that erased approximately $22.4 billion in combined market value. The sell-off has put one of Asia’s strongest-performing equity markets under pressure and raised a critical question: are the losses creating a buying opportunity, or signalling a more sustained deterioration in banking-sector sentiment?
DBS Group Holdings, Oversea-Chinese Banking Corp. (OCBC) and United Overseas Bank (UOB) collectively account for more than half of Singapore’s benchmark Straits Times Index. Their performance therefore has significant implications for the wider market and investor confidence in the city-state’s financial sector. The index has fallen from its recent peak as concerns about earnings downgrades have intensified.
Higher Yields Complicate the Outlook
Higher interest rates have traditionally supported bank profitability by allowing lenders to charge more for loans. However, the relationship is not straightforward. When deposit rates rise faster than lending rates, net interest margins can contract, limiting the benefit of tighter monetary policy.
Higher bond yields can also reduce the market value of existing fixed-income holdings and make bank dividends less attractive relative to competing investments. These pressures have challenged the assumption that rising rates automatically translate into stronger earnings for Singapore’s lenders.
Citi has taken a cautious stance on OCBC, lowering its earnings expectations and downgrading the stock amid concerns about margin pressure and third-quarter performance. The more cautious outlook has contributed to broader investor scrutiny of the sector.
Investors Split Over Buying the Dip
Despite the decline, some analysts believe Singapore’s banks retain attractive long-term characteristics. Their established deposit bases, capital strength, regional wealth-management businesses and dividend distributions remain important advantages.
Other analysts argue that valuations had become demanding after a strong rally earlier in the year. If earnings growth slows, even financially resilient banks could face further share-price pressure as investors adjust their expectations.
The debate is reflected in differing broker recommendations. Some research firms continue to favour the sector on the strength of loan demand and wealth-management activity, while more cautious analysts warn that margin compression and normalising fee income could weigh on results.

Earnings Become the Next Test
The upcoming third-quarter results will be crucial in determining whether the sell-off has gone too far. Investors will focus on net interest margins, loan growth, wealth-management fees, trading income, credit quality and dividend guidance.
The central question is whether earnings can remain resilient despite rising funding costs and a less favourable environment for certain banking activities. Strong capital positions may help absorb pressure, but they cannot entirely protect share prices if profit forecasts are revised lower.
Singapore’s reputation as a regional financial centre and destination for international wealth provides structural support. Nevertheless, those advantages must translate into sustainable earnings growth to justify premium valuations.
What Investors Should Watch
The outlook for Singapore’s banking sector depends on three key factors: whether deposit costs stabilise, whether fee-based income remains strong, and whether valuations become more attractive following the correction.
A recovery in earnings expectations could encourage investors to return to the sector. Conversely, further margin compression or weaker-than-expected results could extend the sell-off.
For investors considering buying the dip, the distinction between a lower share price and genuine value remains essential. The correction has made Singapore’s largest banks more closely watched opportunities, but confirmation from upcoming earnings will be important before the market can establish a more convincing recovery.
Sources
- Bloomberg — Buy-the-Dip Calls Grow After $22 Billion Rout in Singapore Banks
- Bloomberg via Yahoo Finance — Singapore Bank Sell-Off Tests City-State’s Safe Haven Status
- The Straits Times — DBS, OCBC and UOB Shares Fall: Is It Time to Buy?
- The Business Times — DBS, OCBC, UOB Face Rate Hike Reality Check
- UOB Kay Hian — Banking: Second-Quarter 2026 Results Round-up