The rapid expansion of artificial intelligence infrastructure is facing a new financial test as concerns grow over borrowing costs, capital requirements and the sustainability of business models built around AI computing demand. Elon Musk’s warning about potential consolidation among specialist AI cloud providers has put renewed attention on the gap between the industry’s growth ambitions and its ability to generate durable profits.
◉ Consolidation risks increase: Elon Musk warned that many specialist AI cloud providers could fail or be absorbed by competitors as financing conditions become more difficult.
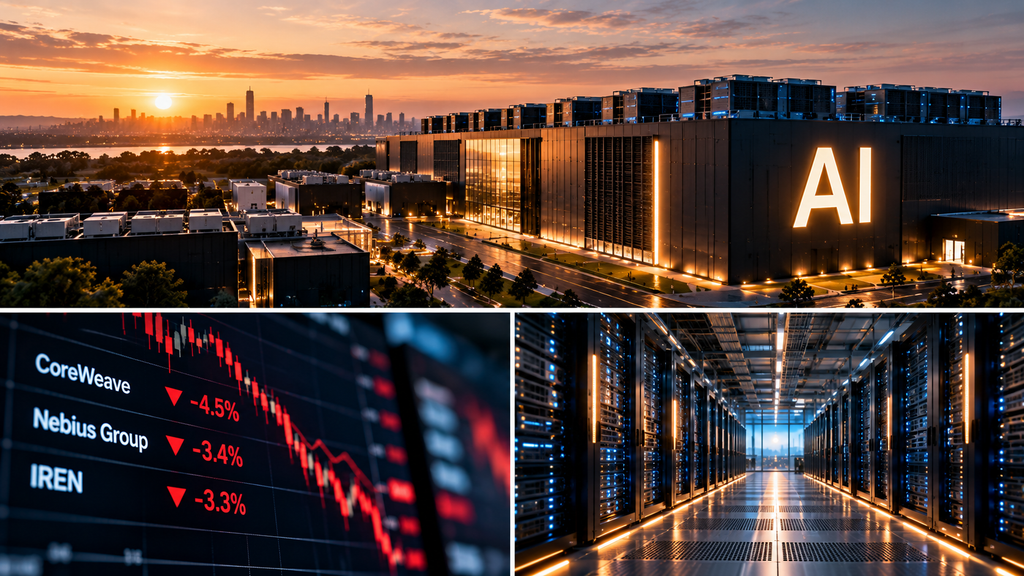
◉ AI infrastructure stocks weaken: CoreWeave fell 4.5% in reported premarket trading, while Nebius Group declined 3.4% and IREN lost 3.3%.
◉ Financing becomes a competitive advantage: Companies investing heavily in data centres must balance large upfront capital commitments with customer demand, operating costs and future cash generation.
The Cost Of AI Expansion
The AI investment boom has created substantial demand for advanced processors, cloud computing capacity, data centres and supporting energy infrastructure. Technology companies are racing to secure computing resources as businesses expand their use of generative AI and other data-intensive applications.
However, building the infrastructure required to serve this demand is expensive. Providers must often commit billions of dollars to equipment, facilities, electricity and networking before their investments generate sufficient revenue to cover the associated costs.
This creates a timing mismatch between spending and cash generation. Companies may secure long-term customer commitments while still facing substantial near-term financing requirements, particularly when infrastructure must be built ahead of demand.
The challenge becomes more pronounced when borrowing costs rise, lenders tighten credit standards or investors demand clearer evidence of profitability.
The resulting pressure does not necessarily indicate that demand for AI computing is weakening. Instead, it raises questions about which companies can finance expansion efficiently and convert infrastructure demand into sustainable earnings.
The Debt Behind the Boom
The sector’s vulnerability has become more visible as investors reassess the relationship between AI infrastructure spending and the revenues required to support it.
A separate market decline earlier in October had already highlighted concerns about heavily indebted AI companies. Rising interest-rate expectations increased financing costs, while investors questioned whether the returns expected from the AI buildout would justify its scale. The latest warning adds to an existing debate rather than introducing an entirely new risk.
One of the most important factors is the lifespan of computing equipment. Advanced processors can lose economic value as new generations arrive, even when demand for computing capacity remains strong. Companies must therefore generate sufficient cash flow during the useful life of their equipment to cover financing obligations and replacement costs.
Debt can accelerate expansion when customer demand is strong. However, it also increases financial exposure when construction is delayed, borrowing becomes more expensive or contracted revenues fail to meet expectations.
For investors, the distinction between an infrastructure company’s announced capacity and its operational, revenue-generating capacity is becoming increasingly relevant.
Why Companies Could Diverge
The outlook for specialist AI cloud providers is unlikely to be uniform. Businesses differ in their financing arrangements, customer concentration, access to capital, construction schedules and ability to generate revenue beyond data-centre operations.
Companies with stronger balance sheets and reliable customer commitments may be better positioned to navigate tighter financing conditions. Those that depend heavily on repeated borrowing could face more difficult decisions about expansion, asset sales or restructuring.
The distinction is important because demand for AI computing can continue growing even as individual infrastructure providers encounter financial distress.
A recent report on the sector’s debt exposure highlighted concerns about rising leverage and the possibility that some providers may cease operating independently. Such projections are scenarios, not confirmed outcomes, but they illustrate the potential consequences of an industry expanding faster than its financing capacity.
Consolidation could eventually redirect computing demand towards larger providers with better access to financing. It could also leave some investors and creditors exposed to losses if struggling businesses cannot meet their obligations.
What Comes Next
The next phase of the AI infrastructure cycle will test whether rapid investment can translate into sustainable financial performance.
Three developments warrant attention:
- Access to financing: Changes in lending conditions, debt pricing and refinancing availability will help determine which providers can continue expanding.
- Capital expenditure discipline: Evidence of delayed projects, reduced investment plans or slower capacity deployment could indicate that companies are adjusting to tighter financial constraints.
- Revenue and cash flow: Customer commitments matter, but realised revenue, operating margins and cash generation will be central to assessing whether infrastructure investments can support their financing costs.
The broader market question is whether the AI sector can maintain its expansion without placing excessive pressure on corporate balance sheets.
Elon Musk’s warning has brought that question back into focus. The underlying issue extends beyond any single company or trading session: AI computing demand and AI infrastructure profitability are related, but they are not the same thing.
The distinction could become increasingly important as capital providers demand clearer evidence that the industry’s enormous infrastructure investments can generate returns over time.