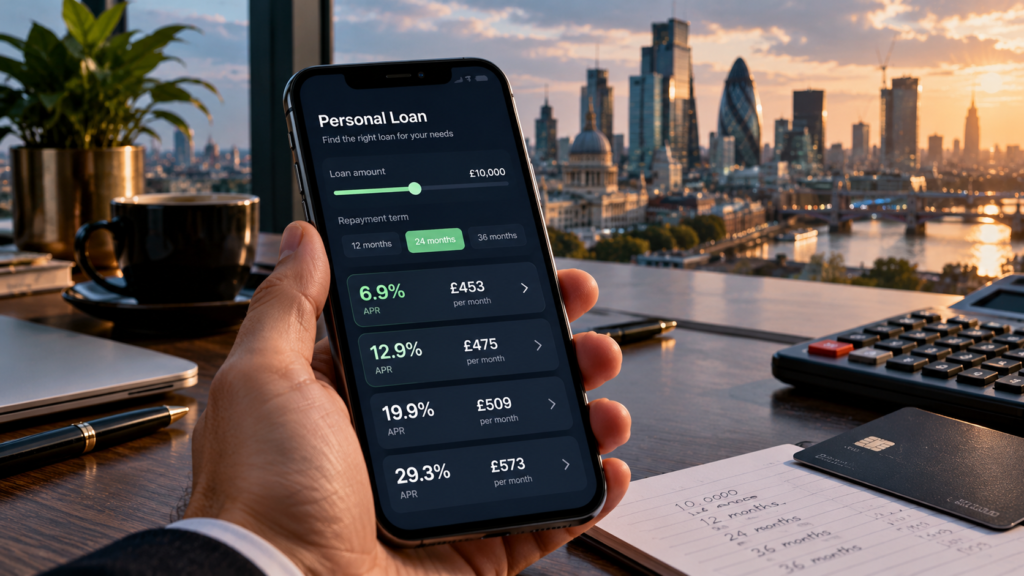
Revolut’s launch of unsecured personal loans in the UK marks another step in its evolution from a payments app into a broader banking competitor. With advertised rates ranging from 6.9% to 29.3%, the move highlights both the commercial opportunity in consumer credit and the importance of individual credit assessments.
◉ A new competitive front: Revolut is entering a UK personal-loan market dominated by established banks, including Barclays, HSBC, Lloyds and NatWest.
◉ Rates reveal borrower risk: The wide advertised interest-rate range reflects how credit history, affordability and individual risk assessments can influence the terms offered to customers.
◉ Growth brings new exposure: Lending could increase revenue per customer, but it also introduces credit losses, funding requirements and regulatory responsibilities.
From Payments to Personal Credit
Revolut has built its international business around mobile payments, foreign exchange, subscriptions and other app-based financial services. Its UK personal-loan launch takes the company deeper into a market where established banks have decades of experience assessing borrowers and managing credit risk.
The new unsecured loans are expected to range from £2,000 to £25,000, with an initial rollout to selected customers before wider availability. The company has also signalled plans to introduce credit cards, with mortgages a longer-term ambition.
The strategy addresses a central challenge for digital financial platforms: attracting millions of customers does not automatically make them the primary provider of those customers’ financial services.
A customer may use a fintech app for travel spending or currency conversion while maintaining their salary account, savings and borrowing relationships elsewhere. Lending gives Revolut another opportunity to become part of customers’ everyday financial decisions.
For established banks, the competitive pressure is not limited to pricing. A digital provider can integrate loan applications, eligibility checks and account information within one mobile interface, reducing friction in the customer journey.
However, convenience alone does not guarantee a sustainable lending business. Credit products require rigorous underwriting, ongoing monitoring and sufficient capital to absorb defaults.
Understanding the Interest-Rate Range
The advertised range of 6.9% to 29.3% is one of the most significant aspects of Revolut’s launch.
Rather than offering every approved customer the same price, lenders typically assess individual applications and assign rates according to their evaluation of risk. Applicants with stronger credit histories and more reliable income may qualify for lower rates, while borrowers perceived as riskier may receive substantially more expensive offers—or be declined altogether.
The headline rate therefore does not necessarily represent the terms available to a particular applicant.
Credit assessments can consider several factors, including repayment history, outstanding debts, income, regular expenditure and the borrower’s ability to manage the proposed repayments. Lenders may also use information from credit-reference agencies and other external data providers.
Revolut’s UK chief executive has said the company supplements its own information with data from external providers. This is relevant because established banks may hold extensive historical records of customer income, spending and repayments.
A digital lender can use technology to process information efficiently, but its assessment models must still distinguish between customers who can comfortably afford repayments and those whose financial circumstances make borrowing more uncertain.
Why Creditworthiness Matters
Creditworthiness is more than a numerical credit score. It is an assessment of whether a borrower is likely to repay a loan and whether the repayments are affordable given their financial position.
A person with a good repayment history may still face affordability concerns if existing debts or regular expenses consume a large proportion of income. Conversely, a borrower with a limited credit history may present a different assessment challenge from someone with a documented pattern of missed payments.
Lenders must balance these factors when determining eligibility and pricing. In the UK, the Financial Conduct Authority requires firms to assess creditworthiness, including affordability, before providing regulated consumer credit.
That responsibility is particularly important in unsecured lending because the loan is not backed by a specific asset such as a house or vehicle. If the borrower defaults, the lender may have fewer straightforward recovery options than it would under certain secured lending arrangements.
Higher interest rates can compensate lenders for some expected losses and operating costs, but they do not eliminate credit risk. If a lender consistently underestimates the likelihood of defaults, even a portfolio charging relatively high rates can produce disappointing financial results.
The Cost of Borrowing Beyond the Headline
The interest rate is only one part of a loan’s overall cost. Borrowers also need to understand the repayment period, monthly instalments, fees where applicable and the total amount repayable over the life of the agreement.
Annual Percentage Rate, or APR, is designed to help consumers compare the annual cost of credit, incorporating interest and relevant mandatory charges. A representative APR in UK credit advertising generally must be offered to at least 51% of successful applicants, although the rate an individual receives can differ.
The distinction matters when a product advertises a wide range of possible rates. The lowest figure may be available only to applicants who meet the lender’s strongest criteria.
Loan duration can also change the economics. A longer repayment period may reduce the monthly instalment but increase the total interest paid, depending on the rate and structure. Two offers with similar monthly payments may therefore have different overall costs if their terms differ.
For digital lenders, presenting personalised offers clearly is both a consumer-protection issue and a test of the quality of the customer experience. A streamlined interface is valuable only if customers can also understand the financial commitment they are accepting.
A New Revenue Engine for Revolut
Personal lending could help Revolut increase the revenue it generates from each customer. Traditional banks often earn substantial income from lending, while Revolut historically relied more heavily on transaction-related fees, subscriptions and other services.
Reuters reporting on the company’s growth has highlighted the gap between its large customer base and its relatively limited lending activity compared with established banks. Expanding consumer credit offers a route to a broader banking relationship.
The opportunity is significant, but the economics are more complicated than simply collecting interest.
A lender must account for funding costs, expected credit losses, operational expenses, compliance, fraud prevention and the capital needed to support its loan portfolio. If competition forces rates lower, the margin remaining after those costs can narrow.
Revolut has indicated that it intends to manage lending exposure carefully and has discussed using securitisation to transfer some credit risk to investors. In a securitisation, a pool of loans can be packaged into financial instruments sold to investors, subject to the transaction’s structure and risk allocation.
Such arrangements can help lenders manage balance sheets and funding, but they do not make the underlying risks disappear. Outcomes depend on loan performance, investor demand and the terms of the transaction.
Established Banks Face a Different Rival
Revolut enters a market where incumbent banks possess substantial advantages, including established deposit bases, long-standing customer relationships and extensive credit histories.
Its competitive proposition is different. A mobile-first platform can make the application process feel more immediate and integrate borrowing with account management, spending data and digital customer support.
That model may appeal to customers who prefer to manage several financial products through a single app. It can also provide a platform for cross-selling additional services, potentially increasing customer retention.
Yet established banks are also investing in digital channels, automated underwriting and personalised financial products. Revolut is not competing against static institutions; it is challenging organisations with large balance sheets and years of experience in managing lending cycles.
The contest will depend on more than app design. Pricing, approval rates, customer service, fraud controls and the quality of credit decisions will all influence whether Revolut can build a durable position in the market.
The Risks Behind Faster Lending
Consumer credit is sensitive to economic conditions. Higher living costs, weaker employment and rising household expenses can reduce borrowers’ capacity to make repayments.
A loan portfolio that performs well during a period of stable employment may experience higher arrears when household finances come under pressure. Lenders must therefore assess not only the borrower’s current circumstances but also the resilience of their portfolio under changing conditions.
Rapid expansion can make this task more demanding. As lending volumes rise, firms need to ensure that credit models remain effective across different customer groups and that operational systems can identify emerging problems.
For Revolut, gradual expansion provides an opportunity to gather performance data and adjust underwriting as the portfolio develops. It also means that the scale and profitability of the UK lending operation will take time to establish.
The company’s longer-term ambitions in credit cards and mortgages would introduce additional competitive and operational challenges. Mortgage lending, in particular, involves larger exposures, longer repayment periods and more complex property-related risks than unsecured personal loans.
What the Launch Signals
Revolut’s move into UK personal lending reflects a wider shift in financial services: digital platforms increasingly want to own more of the customer relationship rather than remain focused on payments alone.
For consumers, additional competition could expand the range of available borrowing products and make it easier to compare offers. But advertised rates are only the starting point. Individual eligibility, total repayment costs and affordability remain central to the actual borrowing decision.
For Revolut, the launch offers a chance to diversify revenue and strengthen its position as a primary banking provider. The challenge is to scale lending without sacrificing underwriting quality or taking on excessive risk.
The defining measure of success will not simply be how many loans the company originates. It will be whether those loans generate sustainable returns after funding costs, defaults and operating expenses—and whether customers can use the product with a clear understanding of its cost.
Digital banking is moving further into traditional financial territory. Revolut’s lending expansion shows that technology can reshape how credit is distributed, while the underlying economics of risk and repayment remain firmly in place.
Sources
- Reuters — Revolut launches personal loans in UK, taking on major banks
- Reuters — Revolut’s rise to become Europe’s $115 billion big bank rival
- Financial Conduct Authority — Consumer credit: sales and advice
- Financial Conduct Authority — Review of how APRs support consumers’ choices
- Revolut — Applying for a personal loan
- Denarni Fokus — Editorial Disclosure & Transparency